TransUnion helps dealers tackle increasingly sophisticated fraud and protect lender relationships.
The customer looks legitimate. Their credit history checks out, they’ve made their payments on time, and there’s nothing particularly suspicious about their application.
But what if the identity behind that credit profile doesn’t actually exist?
It’s a troubling possibility in auto financing, where fraud can remain hidden until an account becomes seriously delinquent.
According to internal research performed by TransUnion Canada, fraud may be behind nearly 30 per cent of seriously delinquent auto loan balances in Canada — an estimated $162 million at risk.
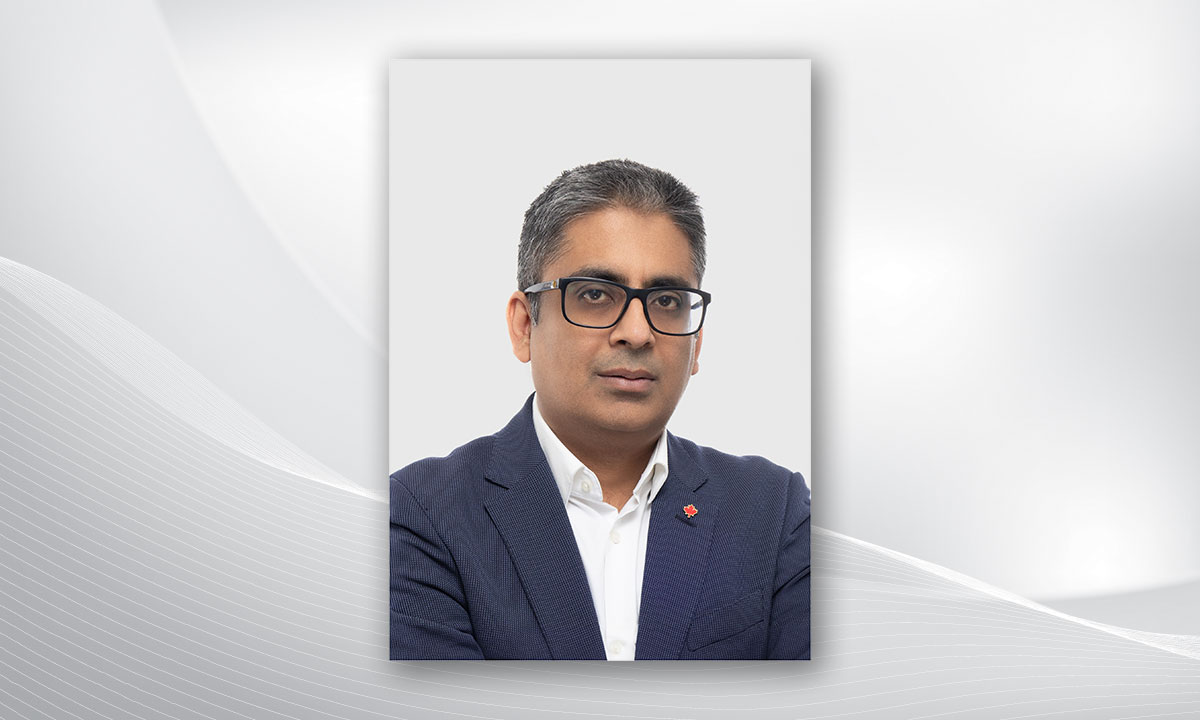
In an interview with Canadian auto dealer, Ashish Khattar, Chief Revenue Officer at TransUnion Canada, said fraudulent loans can be mistaken for ordinary credit defaults. At the end of 2025, Canadians carried nearly $167 billion in outstanding auto-loan debt, according to TransUnion.
For dealerships, the consequences can extend beyond a single transaction.
“If I look at it from a dealer’s perspective, there are two key ways that it will impact them,” said Khattar. “First, there is the financial impact; second, there is the reputational impact.”
Dealers can face chargebacks, funding delays, additional administrative work, and potential damage to lender relationships. Repeated fraud issues may lead to closer scrutiny of future applications, potentially creating more friction in the financing process.
“Dealers should ask themselves a simple question: Are we only verifying the document, or are we verifying the person behind the application?” — Ashish Khattar, Chief Revenue Officer at TransUnion Canada
A convincing disguise
One of the most difficult threats to detect is synthetic identity fraud. Rather than simply stealing another person’s identity, criminals create or manipulate an identity and build a credit record over time, sometimes making regular payments for months or years.
“Lenders have expanded approval strategies to serve consumers with limited credit history,” said Khattar. “The fraudsters have taken advantage of that opportunity by creating or cultivating synthetic identities that initially would resemble a legitimate borrower.”
The deception may end in a so-called bust-out, when the fraudster seeks large amounts of credit, sometimes from several lenders in quick succession, before abandoning the debts. By then, an apparently reliable borrower may have left the lender facing a significant loss.
Starting with credit
Moving credit assessment and identity verification earlier in the sales process, says Khattar, can help to address downside risks in a more efficient manner. “It has to be a mindset shift as well,” said Khattar.
With appropriate customer consent, a credit-first approach can help dealers assess creditworthiness, existing obligations, and potential financing options before investing hours in a transaction that may not qualify for financing.
It’s much like obtaining mortgage pre-approval before house hunting. Customers can understand what they can realistically afford, while helping dealers steer them toward vehicles and lenders that may be a better fit.
An early credit review isn’t, by itself, a fraud check. But combining financing discussions with identity and fraud screening can give dealers and their lending partners more data to help make an informed decision before a deal is finalized.
Looking beyond the documents
Established in Canada in 1989 and headquartered in Toronto, TransUnion Canada provides credit information, identity verification and risk management solutions to financial institutions and the automotive sector. Its consumer credit bureau data covers approximately 31 million Canadians.
While a document check may confirm that identification appears authentic, it won’t necessarily reveal suspicious activity behind an apparently sound credit profile. TransUnion’s Identity Exchange solution draws on credit histories, inquiry records and fraud data from participating organizations to assess risks that individual documents or conventional credit checks may miss.
The solution produces a score that indicates the level of synthetic or first-party fraud risk. Unlike synthetic fraud, first-party fraud involves someone using their own identity to obtain credit without intending to repay it.
“Dealers should ask themselves a simple question: Are we only verifying the document, or are we verifying the person behind the application?” said Khattar.
Unusual patterns, such as a sudden burst of credit applications, may warrant closer examination. TransUnion Canada also draws on reports of confirmed fraud to refine its detection models.
For dealers, the practical starting point is a conversation with lending and financing technology partners: When are identity and fraud checks performed, what warning signs can be shared with the dealership, and what further verification may be required before funding? The process and information available will depend on those arrangements.
Khattar advised that the level of scrutiny can be modified to address a customer’s needs.
“The objective isn’t to make every customer go through additional steps. If it’s a low risk, then don’t create a lot of friction for that customer,” said Khattar. “But if the risk is high, then you may have to do a second or a third level of due diligence.”
The aim is identify applications that may warrant additional review earlier without making legitimate customers jump through unnecessary hoops.
For dealers, knowing whether a customer qualifies for financing is only one part of the decision. Knowing who is actually behind the application is becoming just as important.